For NRI investment in Mumbai real estate, 2026 presents one of the most compelling windows in decades. With the Indian rupee at favorable levels, FEMA regulations streamlined for easier transactions, and premium micro-markets like Chembur delivering 8-12% annual appreciation, Non-Resident Indians have a unique opportunity to acquire luxury assets in one of the world's fastest-growing property markets. This complete guide covers everything an NRI needs to know — from FEMA regulations and home loan eligibility to tax benefits, repatriation rules, and why Hiranandani Maitri Park in Chembur is the ideal NRI investment target in 2026.
Mumbai has always been India's most prestigious real estate market, and NRIs have historically been among the most active buyer segments in the luxury category. In 2026, the convergence of favorable exchange rates, simplified regulations, infrastructure upgrades in emerging suburbs, and trusted developer brands creates an environment where NRI investments are not just safe — they are potentially transformative for long-term wealth creation.
Why NRIs Should Invest in Mumbai Real Estate in 2026
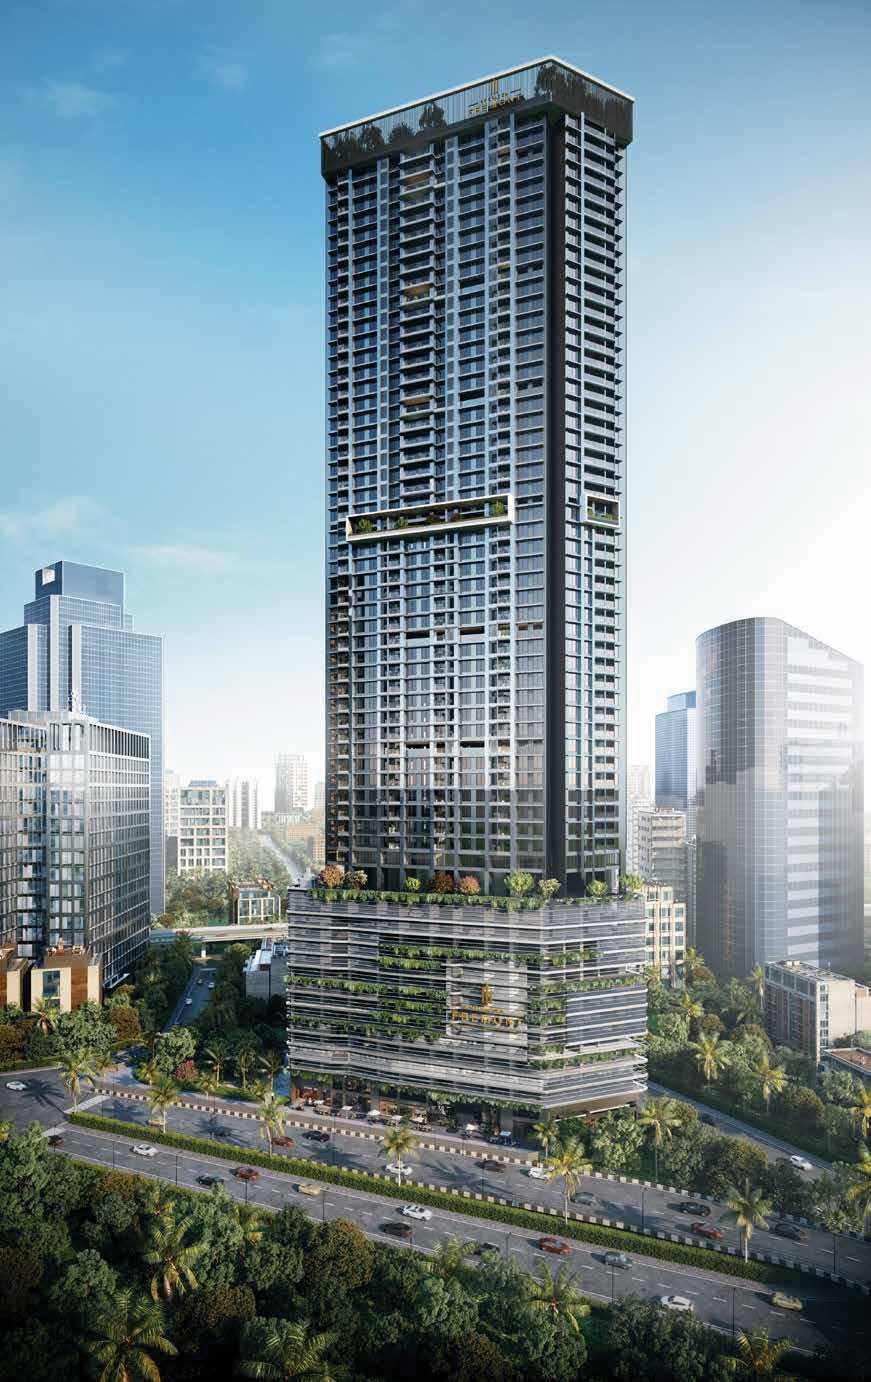
Mumbai's real estate market offers NRIs several unique advantages that are difficult to find in other global cities. The combination of strong rental yields (3-4%), double-digit capital appreciation in emerging corridors, and relatively affordable entry points compared to London, Singapore, or Dubai makes Mumbai a compelling destination. Key factors driving this opportunity include:
- Favorable Exchange Rates: The Indian rupee offers strong purchasing power for USD, GBP, EUR, and AED holders
- Infrastructure Boom: Metro expansions, new airports, and freeway connections are creating premium micro-markets with significant upside
- Regulatory Clarity: RERA and GST have created a transparent, buyer-friendly market that reduces NRI risk
- Digital Transactions: Online payment systems, digital KYC, and remote registration make property purchase possible without physical presence
- Diaspora Confidence: Record NRI property transactions in 2025-2026 indicate strong market confidence among overseas Indians
For NRIs seeking both capital appreciation and emotional connection to India, Mumbai's luxury real estate market — particularly in emerging corridors like Chembur with its multi-modal connectivity — offers the perfect balance of financial returns and homeland investment.
FEMA Regulations: What NRIs Need to Know
The Foreign Exchange Management Act (FEMA) governs all property transactions by NRIs in India. Understanding these regulations is essential for compliant and smooth property acquisition.
Interested in Hiranandani Maitri Park?
Starting at ₹3.95 Cr* — 2, 3 & 4 BHK Golf Course Facing Luxury Residences
MahaRERA: PR1180002600200 | T&C Apply
Eligibility and Property Types
- Who qualifies as NRI: Indian citizens residing outside India for employment, business, or any purpose indicating indefinite stay abroad
- PIO/OCI cardholders: Enjoy the same property purchase rights as NRIs under FEMA
- Residential properties: NRIs can purchase any number of residential apartments and houses
- Commercial properties: NRIs can purchase offices, shops, and commercial spaces
- Restricted categories: Agricultural land, farmhouses, and plantations CANNOT be purchased without prior RBI approval
Payment and Funding Rules
- NRE Account: Fully repatriable — funds deposited can be freely transferred outside India
- NRO Account: Used for income earned in India (rent, dividends) — repatriation allowed up to USD 1 million per financial year after taxes
- Home Loans: Available from SBI, HDFC, ICICI, Axis — typically up to 80% of property value
- Payment Timeline: Full payment must be made within 180 days of booking/registration
For NRIs considering Hiranandani Maitri Park apartments, the FEMA regulations are straightforward — NRI buyers have full eligibility to purchase 2, 3, or 4 BHK units using NRE/NRO funds or Indian home loans. The RERA-registered project status further simplifies due diligence.
Step-by-Step NRI Property Buying Process
Step 1: Research and Shortlisting
Identify the micro-market matching your investment goals. For luxury properties, evaluate connectivity, developer reputation, RERA status, and appreciation potential.
Step 2: Due Diligence
- Verify RERA registration on the MahaRERA website
- Check the developer's track record and delivery history
- Review title documents through a property lawyer
- Verify approved building plans and environmental clearances
- Assess the developer's financial health and project completion timeline
Step 3: Power of Attorney
If you cannot visit India, execute a Power of Attorney in favor of a trusted person, notarized at the Indian Embassy/Consulate. The PoA must be specific to the property transaction and valid for the transaction duration (6-12 months).
Step 4: Booking and Payment
- Pay the booking amount (typically 10%) via NRE/NRO cheque or NEFT/RTGS
- Receive the Allotment Letter confirming your booking
- Execute the Agreement for Sale within the stipulated timeline
- Pay stamp duty and registration charges (approximately 6-7% in Maharashtra)
Step 5: Loan Processing (if applicable)
NRI home loans require PAN Card, passport copy, valid visa, overseas employment proof, income tax returns, and 6-12 months of NRE/NRO bank statements.
Step 6: Registration and Possession
- Register the sale deed at the Sub-Registrar office (can be done via PoA)
- Pay the balance amount as per the 25:75 payment plan
- Receive possession and complete occupancy formalities
- Update property records and utility connections
Tax Benefits for NRI Property Buyers
| Tax Benefit | Section | Maximum Deduction | Applicable To |
|---|---|---|---|
| Principal Repayment | Section 80C | Rs.1.5 lakh/year | Home loan borrowers |
| Interest on Home Loan | Section 24(b) | Rs.2 lakh/year (self-occupied) | Home loan borrowers |
| Additional Interest Deduction | Section 24(b) | Unlimited (let-out property) | Rental property owners |
| Affordable Housing Bonus | Section 80EEA | Rs.1.5 lakh/year | Property value up to Rs.45 lakh |
| Stamp Duty Deduction | Section 80C | Included in Rs.1.5 lakh | First-time buyers |
| Capital Gains Exemption | Section 54 | Full exemption (reinvest in new property) | Sale proceeds reinvested |
NRIs investing in Hiranandani Maitri Park can leverage these tax benefits effectively. The project pricing of Rs.3.95 Cr* across 2, 3, and 4 BHK configurations means NRI buyers can maximize Section 24 interest deductions on let-out properties while building a high-appreciation asset in Chembur.
Repatriation Rules: Getting Your Money Back
One of the most common concerns for NRI investors is repatriation of sale proceeds. FEMA provides clear guidelines:
- Residential Properties: NRIs can repatriate sale proceeds of up to TWO residential properties
- Repatriation Limit: Up to USD 1 million per financial year from NRO account after applicable taxes
- NRE Account Funds: Fully repatriable without limit
- Capital Gains: Repatriation permitted after paying applicable taxes (20% LTCG or 30% STCG)
- Documentation: CA certificate, Form 15CA/15CB, sale deed, bank statements, and tax clearance
- Timeline: Typically completed within 30 days of filing required documents
This framework ensures that NRI buyers at Hiranandani Maitri Park have a clear exit strategy with full repatriation capability for their investment plus appreciation.
Why Chembur and Hiranandani Are Ideal for NRI Investors
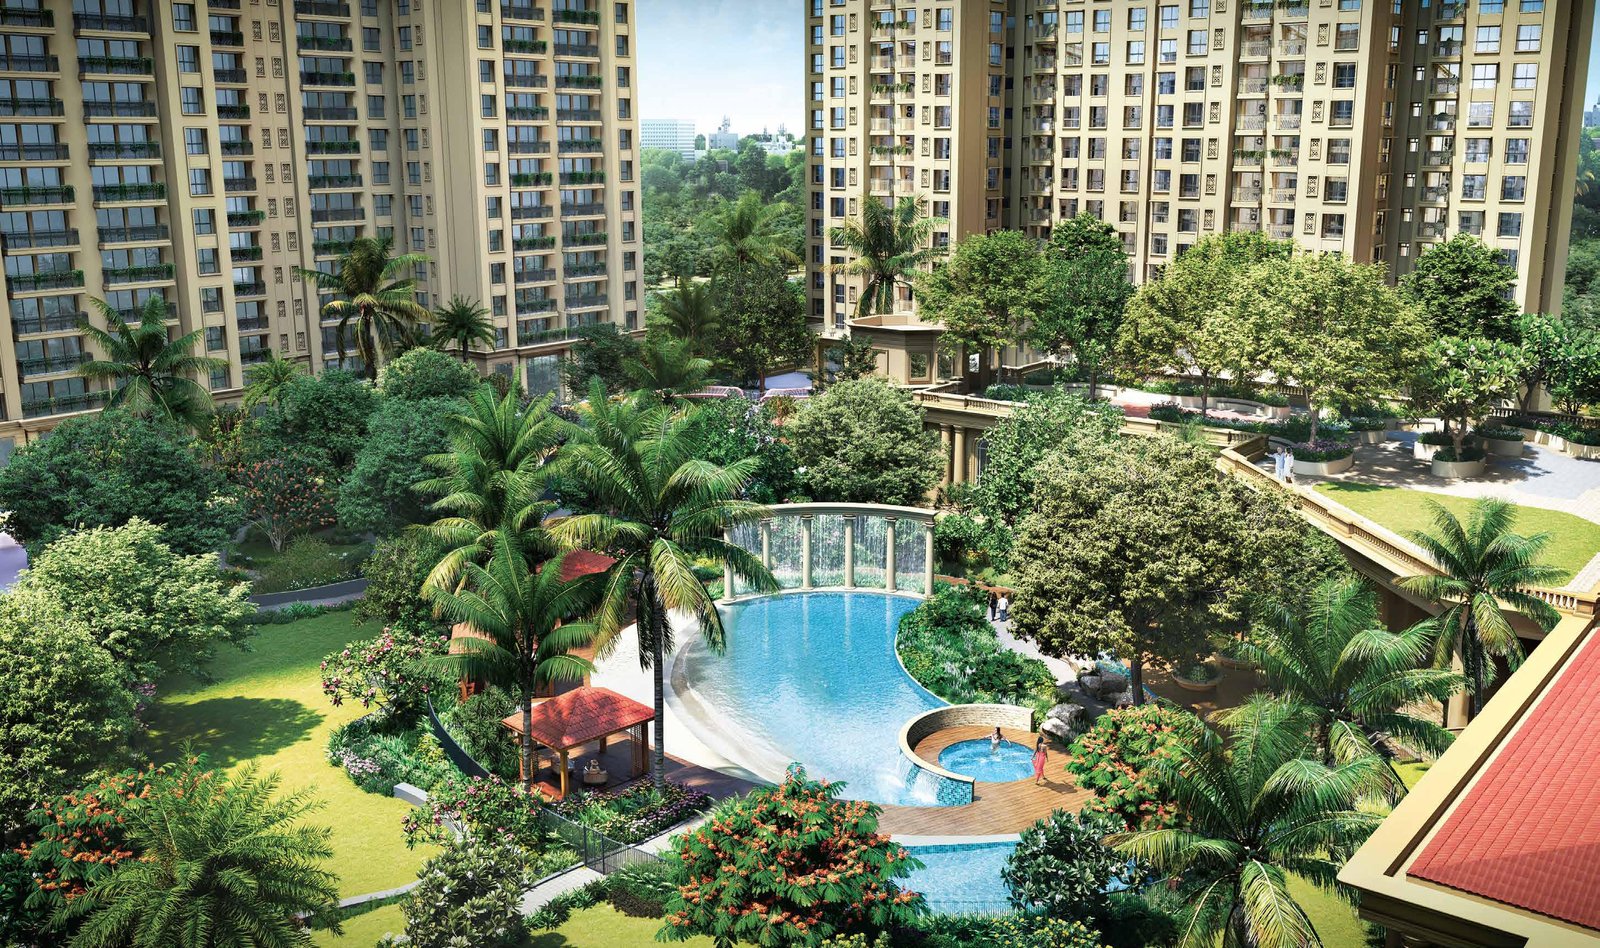
For NRIs who may not be physically present to manage their investment, the combination of location, developer reputation, and infrastructure growth is critical. Chembur and House of Hiranandani deliver on all three fronts.
Chembur's Investment Merit for NRIs
- Appreciation Trajectory: 8-12% annual growth among the highest in Mumbai luxury segment
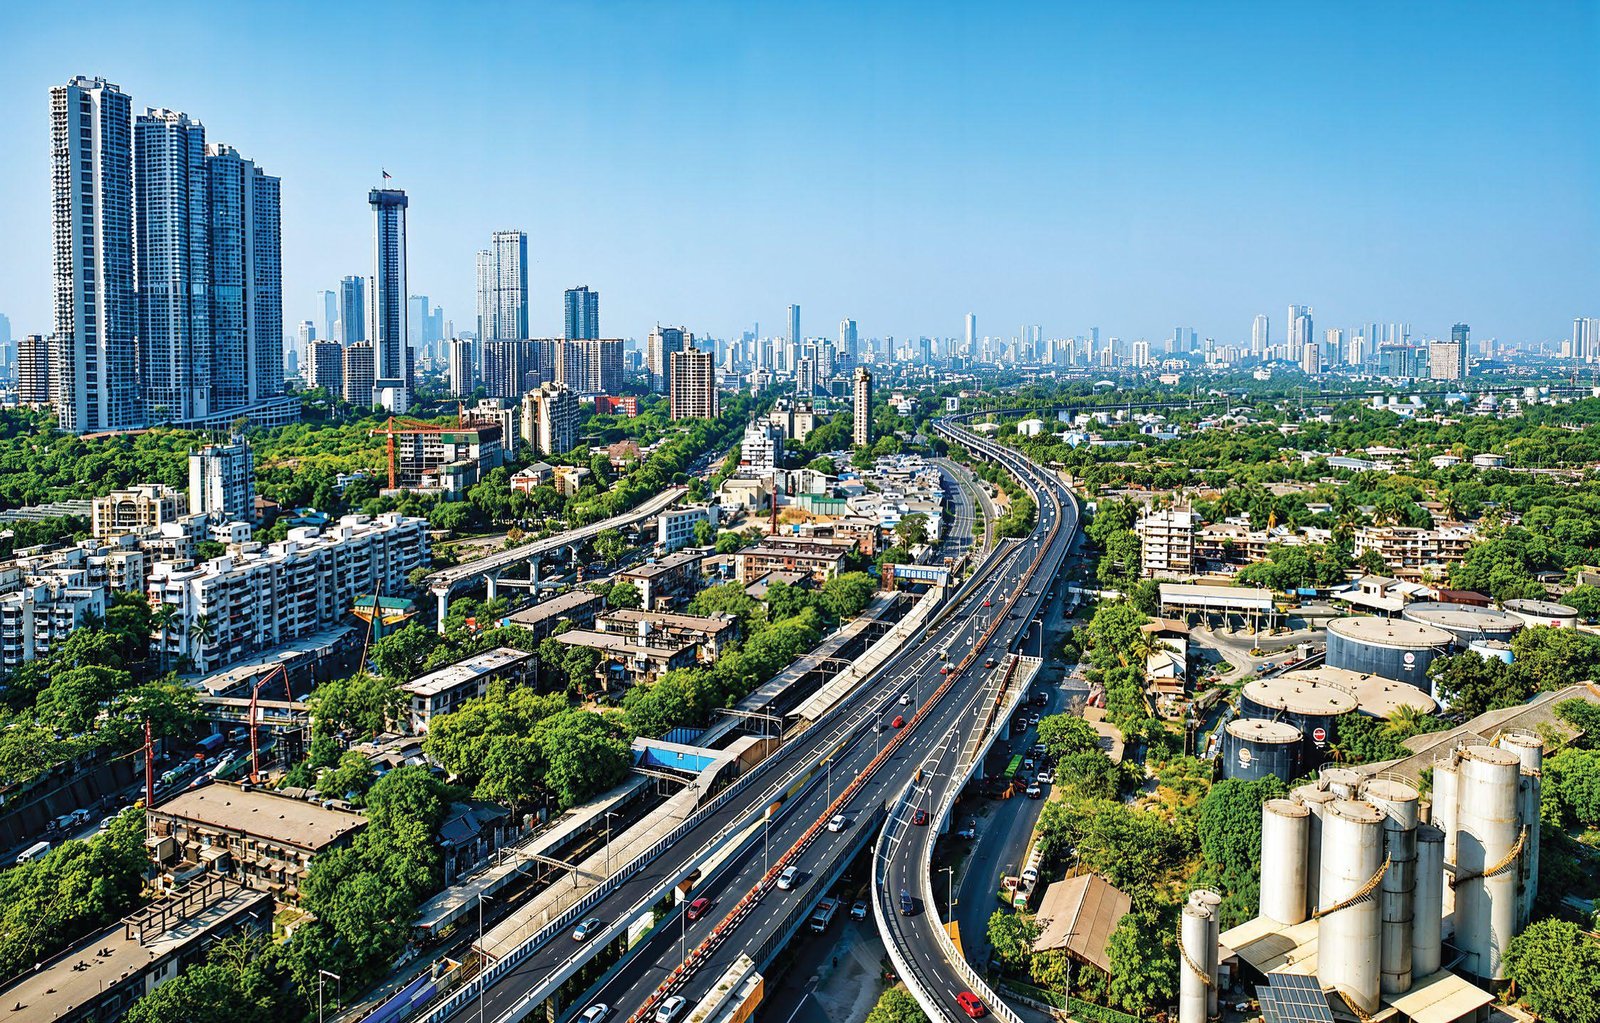
- Infrastructure Momentum: Eastern Freeway, SCLR, Monorail, and upcoming metro create sustained demand
- Corporate Proximity: 15-20 minutes to BKC with highest rental demand in Mumbai
- Golf Course Premium: Properties adjacent to BPGC command 15-25% higher resale values
- Rental Yield: 3-4% annually — competitive for luxury segments globally
House of Hiranandani: The NRI-Friendly Developer
- 40+ Year Legacy: Established in 1978, delivering across Mumbai, Pune, and Chennai
- Track Record: Over 10,000 families served with consistent on-time delivery
- Brand Trust: Recognized as one of India's most trusted real estate brands
- RERA Compliance: All projects registered with MahaRERA — full regulatory transparency
- NRI Services: Dedicated NRI desk for remote transactions and post-sale property management
- Proven Track Record: Successfully delivered Hiranandani Gardens Powai and Hiranandani Estate Thane
NRI Investment Comparison: Mumbai vs Other Global Cities
| Parameter | Mumbai (Chembur) | London | Dubai |
|---|---|---|---|
| Entry Price (Luxury 3 BHK) | Rs.4-8 Cr | GBP 1.5M-3M | AED 3M-6M |
| Annual Appreciation | 8-12% | 3-5% | 5-8% |
| Rental Yield | 3-4% | 2-3% | 5-7% |
| Capital Gains Tax | 20% (after indexation) | 18-28% | 0% |
| Transaction Costs | 6-7% | 7-10% | 4% |
5-Year Investment Projection: Hiranandani Maitri Park
Projected returns for an NRI investing in a 3 BHK at Maitri Park in 2026:
| Year | Investment | Appreciated (10% CAGR) | Cumulative Rental |
|---|---|---|---|
| 2026 | Rs.5.5 Cr | Rs.5.5 Cr | Rs.0 |
| 2027 | Rs.5.5 Cr | Rs.6.05 Cr | Rs.16.5 L |
| 2028 | Rs.5.5 Cr | Rs.6.66 Cr | Rs.34.1 L |
| 2029 | Rs.5.5 Cr | Rs.7.32 Cr | Rs.52.8 L |
| 2030 | Rs.5.5 Cr | Rs.8.05 Cr | Rs.72.6 L |
| 2031 | Rs.5.5 Cr | Rs.8.86 Cr | Rs.93.5 L |
Common NRI Investment Mistakes to Avoid
- Skipping Due Diligence: Always verify RERA registration, title clarity, and developer history before committing
- Ignoring Tax Implications: Consult a CA specializing in NRI taxation to optimize TDS and capital gains
- Not Using NRE Accounts: NRE funds are fully repatriable — always route purchase through NRE where possible
- Choosing Unknown Developers: Stick with established brands like House of Hiranandani
- Ignoring Location Fundamentals: Prioritize connectivity and infrastructure pipeline — review our connectivity guide for details
- Overlooking Maintenance Costs: Factor in society charges, property tax, and renovation costs for rental properties
Documents Required for NRI Property Purchase
- Identity: Valid passport, OCI/PIO card (if applicable), PAN card
- Address Proof: Overseas utility bill, bank statement, or driving license
- Income Proof: Salary slips, employment contract, overseas tax returns
- Bank Documents: NRE/NRO account statements (6-12 months), cancelled cheques
- Power of Attorney: Notarized at Indian Embassy/Consulate (if not visiting India)
- Photographs: Passport-size photographs (6-8) for registration
Understanding RERA Protection for NRI Buyers
The Real Estate Regulation and Development Act (RERA) provides critical protection for NRI buyers by ensuring project transparency, timely delivery, and escrow account maintenance. Hiranandani Maitri Park's RERA registration (PR1180002600200) means that every detail — from carpet area to completion timeline — is publicly verifiable on the MahaRERA website.
Chembur vs BKC: Where Should NRIs Invest?
For NRIs evaluating Chembur vs BKC, the numbers clearly favor Chembur. While BKC offers walking-distance corporate access, its entry prices of Rs.40,000-65,000 per sq ft limit apartment sizes and appreciation potential. Chembur, with 8-12% annual appreciation vs BKC's 5-8%, offers superior ROI for NRI investors with a 5-10 year horizon. For a deeper analysis of Chembur's luxury property landscape, our comprehensive comparison covers pricing, connectivity, and lifestyle factors.
Invest in Hiranandani Maitri Park as an NRI
Starting at Rs.3.95 Cr* — 2, 3 & 4 BHK Luxury Residences in Chembur
25:75 Payment Plans — T&C Apply* | MahaRERA: PR1180002600200
Unlock Pricing & Floor Plans WhatsApp UsFrequently Asked Questions
Can NRI buy property in Mumbai without visiting India?
Yes, NRIs can purchase property in Mumbai without physical presence by executing a Power of Attorney (PoA) in favor of a trusted person. The PoA must be notarized at the Indian Embassy or Consulate in the NRI's country of residence. Some developers like House of Hiranandani also facilitate remote transactions through authorized representatives and digital documentation processes.
What is the maximum number of properties an NRI can buy in India?
Under FEMA regulations, NRIs can purchase any number of residential and commercial properties in India without prior approval from the RBI. However, agricultural land, farmhouses, and plantations cannot be purchased by NRIs without special RBI permission. There is no cap on residential or commercial property purchases.
Can NRI avail home loan in India for buying property?
Yes, NRIs can avail home loans from Indian banks including SBI, HDFC, ICICI, and Axis Bank at competitive interest rates. The loan amount is typically up to 80% of the property value, and repayment can be done through NRE or NRO accounts. Most banks require a minimum salary of USD 3,000 per month or equivalent for NRI home loan eligibility.
What are the tax benefits for NRI property buyers in India?
NRIs can claim tax deductions under Section 80C (up to Rs.1.5 lakh on principal repayment), Section 24 (up to Rs.2 lakh on interest for self-occupied property, unlimited for let-out), and additional deductions under Section 80EEA. TDS is applicable at 20% on long-term capital gains and 30% on short-term gains. NRIs can file ITR to claim refunds if TDS exceeds actual tax liability.
How can NRIs repatriate the sale proceeds of property in India?
NRIs can repatriate sale proceeds of up to two residential properties held in India. The repatriation limit is the foreign exchange equivalent of the original investment amount plus capital gains, capped at USD 1 million per financial year from the NRO account. NRE account funds are fully repatriable. Documentation required includes CA certificate, Form 15CA/15CB, sale deed, bank statements, and tax clearance.
Why is Chembur a good investment location for NRIs in 2026?
Chembur offers NRIs strong appreciation potential (8-12% annually), proximity to BKC's business hub (15-20 minutes), infrastructure upgrades including metro, freeway, SCLR, and monorail, and the credibility of established developers like House of Hiranandani. The suburb's transformation mirrors successful NRI investment patterns in Powai and Thane. Golf-course-adjacent properties like Hiranandani Maitri Park command premium resale values, making them especially attractive for long-term NRI wealth creation.